The short answer
What are the best business loans for an equipment purchase?
For most operators, equipment financing, where the machine secures its own loan: low or no money down, a personal guarantee is the exception, and it runs $250K–$25M per asset, with larger transactions available when revenue, cash flow, and equipment value qualify. A bank is slow and selective, on a 30–60 day cycle; the specialist lender network funds files under $1M in as little as 2 days and returns a proposal on $1M+ files in 24–48 hours.
The Real Problem
The Order's in Hand. The Only Thing Missing Is the Machine to Fill It.
Paying cash would drain the capital you need to actually run the work — and waiting on a bank cycle means the delivery window closes before the equipment ever arrives.
A machine you've paid cash for doesn't help if the cash was what you needed to staff and run the work — and a bank cycle that funds after the delivery window closes isn't financing, it's a missed order.
What you actually need is the equipment financed on the asset itself — fast enough to hold the delivery window, with your cash left in the business.
Bobby’s Take
I've watched operators write a check for the whole machine because it felt responsible, then scramble for working capital to run the very work the machine won. The equipment can secure itself — finance it on the asset, hold your cash, and hit the delivery date.
Bobby Friel, Founder, Basecamp Funding
Capital Stacking in Action
How a $2.4M Equipment Loan Anchored a $4.2M Re-Tool for a $26M Manufacturer
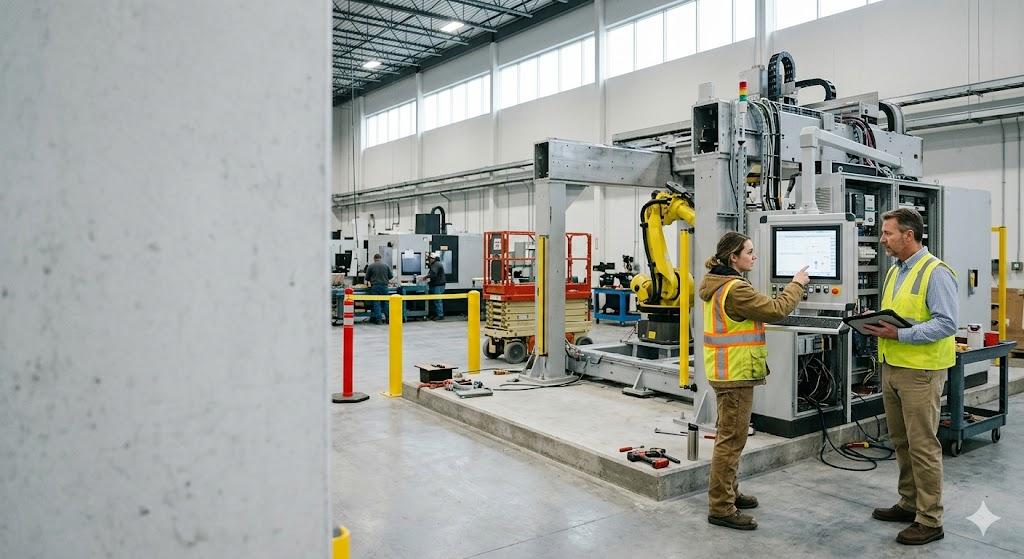
A precision manufacturer at $26M revenue won a multi-year contract that required three new CNC machining centers and an automation cell. The equipment secured its own layer; operations and receivables stacked on top.
The line was on the floor in time for the contract start, the machines secured their own financing — no building pledged — and the payments were matched to the equipment's useful life.
The $4.2M structure, one application
One application · one specialist desk
Funded Scenarios
Equipment We've Financed for Operators Like You
Representative scenarios — illustrative, anonymized figures, not specific client transactions.


What operators tell us
“We were about to write a check for the whole machine because that's what felt responsible. The specialist desk showed us the machine could secure its own financing — low money down, no building pledged — and the line throws off more than the payment. We kept our cash in the business and still got the equipment on the floor on time.”
Operator · $23M precision manufacturer
Start Here
See What the Equipment Qualifies For — in About 60 Seconds
Set the equipment cost, tell us a little about the business, and the specialist desk reads the file. No application fee. No credit ding to look. Real term sheet proposals — not a dealer’s single quote.
Soft-pull only · Financials or bank statements, depending on file size · Real term sheets, not estimates
Estimate Your Equipment Financing
Slide to the equipment cost — one machine, a line, a fleet, or a buildout.
Equipment amount
Equipment cost — add install and soft costs on $1M+ projects.
Your structure comes from the term sheet proposal, not a quote.
Your actual terms come from real term sheets.

How It Works
How Commercial Equipment Financing Is Actually Structured
Equipment financing is capital to acquire an asset, where the financed equipment itself secures the facility — loan or lease, term matched to the equipment's life, often with low or no down payment. Here's the real mechanic at this level.
Above $1M, for operators at $10M+ in revenue, the file moves to the large-ticket desk: financials instead of bank statements, operating or capital lease on the table, and a term sheet proposal in 24–48 hours. A project with several vendors and a build phase is capex financing; equipment you already own and need the cash out of is a sale-leaseback; stacking the equipment layer with working capital or real estate is commercial financing.
The Cost of Waiting
Every Week the Equipment Isn't on the Floor, the Capacity Gets Quoted by Someone Who Already Has It
Finance the asset and move now — the equipment is on the floor before the window closes.
Structure Your Capital Plan →Compare the Options
Equipment Financing vs the Alternatives
| Equipment Financing | Equipment Lease | Bank Equipment Loan | Cash Purchase | |
|---|---|---|---|---|
| Ownership | You own it — builds equity | Lessor owns; you use | You own it | You own it |
| Down payment | Low or none | First/last + fees | Often 10–20% | 100% upfront |
| Collateral | The equipment itself | The equipment | Equipment + often more | None — but cash is gone |
| Speed to fund | Days | Days | 30–60 days | Immediate, but drains cash |
| Best for | Owning the asset, keeping cash working | Short-life / fast-upgrade gear | Bank-fit borrowers who can wait | Rarely the right move |
Bobby’s Take
“Operators love paying cash for equipment because it feels responsible. It usually isn't. The machine throws off more than the financing costs, so paying cash ties up capital that should be running the business to save a rate you could've matched anyway. And here's what the bank won't volunteer — the equipment secures itself. You shouldn't be pledging your building and signing a full personal guarantee to buy a press brake. Let the asset carry the loan and keep your cash and your collateral where they belong.”
Bobby Friel · Founder, Basecamp Funding · 20+ years in banking and finance
Straight Answers
The Straight Answers Operators Ask For
Why finance equipment instead of paying cash?
Cash spent on a machine is cash not running the business — finance the asset and keep the cash working, because the equipment pays for itself out of what it produces.
Won't the lender want my building and a full personal guarantee too?
Usually not — the equipment is the collateral, so a personal guarantee is the exception, not the bank's full-PG default.
My bank quoted a rate on the equipment — can you beat it?
A generalist bank blends the whole loan at its riskiest layer; an equipment lender prices the machine at its own wheelhouse, and you compare real term sheets, not one quote.
The dealer already offered me financing.
Dealer financing ties you to one vendor's single quote — vendor-neutral financing brings competing term sheets on the same equipment, so the asset sets the terms, not the dealer.
I need it before delivery, and the price expires.
Low or no down payment and funding in as little as 2 days mean the delivery window and the early-purchase price don't slip while the paperwork drags.
I'm buying more than $5M of equipment.
Good. The equipment form runs to $25M, and a $1M+ file for an operator at $10M+ in revenue goes to the large-ticket desk: two years of financials, a term sheet proposal in 24–48 hours, 100% of hard and soft costs, operating or capital lease on the table. Several vendors and a build phase is capex financing.
Get the equipment working now on real term sheets, and optimize later.
Fund the asset today on real term sheets; as payment history builds, both your terms and your access to additional capital improve. You don't wait for perfect to put the equipment to work.
The Process
How Equipment Financing Comes Together
Submit your file.
Signed application + 4 months business bank statements + the invoice or quote for the equipment. No application fee, soft-pull only.
A specialist reads the file and the asset.
An advisor reads your cash flow and the equipment itself — what it's worth, what it produces — and matches the structure to the asset.
Real term sheets come back.
Equipment lenders return actual, fundable offers priced to the machine — not a generalist's blended quote, and not a single dealer's number.
You pick the structure and fund.
Choose the term sheet that fits; low or no down payment, term matched to the equipment's useful life, funding in as little as 2 days.
The equipment anchors the plan.
Use it as the asset layer, keep the line free for operations, and stack working capital, A/R, or real estate as the structure grows toward $20M+.
Self-Qualify
Who Equipment Financing Fits — and Who It Doesn't
Before You Apply
What Kills an Equipment-Financing Application
Straight talk on what stops equipment financing before it starts — so you fix it before you submit.
By Industry
Equipment Financing by Industry
The equipment secures the financing in every industry — the production line, the fleet, the imaging suite, the iron. Explore the fit for yours.
Manufacturing
Finance a CNC line, presses, or an automation cell on the machines themselves — low or no down, term matched to the equipment's life.
Healthcare
Add imaging suites, CBCT, or operatory equipment with the asset as collateral — compare real term sheets, not one vendor quote.
Trucking & Logistics
Finance a fleet on the iron itself — minimal down payment, term matched to the trucks' useful life.
Restaurants & Franchise
Outfit a kitchen buildout — hoods, walk-ins, line equipment — secured by the equipment so the line stays open.
Construction & Heavy Industrial
Add excavators, dozers, and crushers on the iron — capture early-purchase pricing with the term matched to the equipment.
Distribution & Wholesale
Automate a warehouse — forklifts, conveyor, racking — with the equipment as collateral and the cash kept for inventory.
Run your machine through the equipment financing calculator for the monthly, the total cost, and the Section 179 deduction in year one.
For the tax side on its own — 179 vs bonus, the phase-out, the lease question — use the Section 179 calculator to see the first-year write-off at your bracket.
FAQs
Equipment Financing — Questions Operators Actually Ask
For most operators, equipment financing, where the machine secures its own loan: low or no money down, a personal guarantee is the exception, and it runs $250K–$25M per asset, with larger transactions available when revenue, cash flow, and equipment value qualify. A bank is slow and selective, on a 30–60 day cycle; the specialist lender network funds files under $1M in as little as 2 days and returns a proposal on $1M+ files in 24–48 hours.
Equipment financing is capital to acquire business equipment — machinery, vehicles, medical and imaging systems, kitchen, IT and data-center hardware — where the equipment itself secures the loan. At the commercial level it runs $250K–$25M, structured as a loan or lease with a term matched to the equipment's useful life (typically 1–5 years), often with low or no down payment. Under $1M it funds on bank statements in as little as 2 days; $1M+ files for $10M+ operators are underwritten on financials with a proposal in 24–48 hours.
Financing means you own the equipment and build equity in it; leasing means the lessor owns it and you use it. Own it when you'll keep the asset and it holds value (production machinery, fleet, imaging). Lease when the gear is short-life or you'll upgrade quickly (some IT). The specialist desk structures whichever fits the asset and how long you'll run it.
Often little or none. Because the equipment secures the loan, low or no-down-payment structures are common — you keep your cash in the business instead of sinking it into the purchase.
The page floor is 600+, and equipment financing is among the more flexible products because the asset secures the facility. Consistent deposits and the equipment's value carry the file; challenged credit in the 600–700 range is workable, and your terms reflect the risk.
Usually not. The equipment is the collateral, so a personal guarantee is the exception, not the default — you shouldn't have to pledge your building to buy a machine. The structure is built around the asset itself.
Under $1M: as little as 2 days once the file and the quote are in. $1M+: a term sheet proposal in 24–48 hours and funding in 2–10 business days from a signed proposal. Either way, faster than a 30–60 day bank cycle.
Production machinery and automation (CNC, presses, robotics), commercial fleets, medical and imaging equipment, restaurant and kitchen buildouts, IT and data-center hardware (servers, GPUs, cooling, networking), and heavy industrial iron (excavators, dozers, crushers). If it has real resale value, it can usually secure its own financing.
$250K–$25M. Under $1M the equipment funds on four months of bank statements; $1M+ files for operators at $10M+ in revenue go to the large-ticket desk on two years of financials. Above $25M, or for a whole plant, commercial financing stacks the equipment as one layer.
Yes. The equipment form runs to $25M, and $1M+ files for operators at $10M+ in revenue go to the large-ticket desk on two years of financials. Above $25M, or for a whole plant, the structure is commercial financing with the equipment as one layer.
Yes on $1M+ files for $10M+ operators: equipment, rigging, electrical, software, freight, and training on one facility. Under $1M the equipment funds at low or no money down and the soft costs are usually yours. A project with several vendors and a build phase is capex financing.
Vendor location is logistics, not credit. The file needs the quote, the payment schedule, and the delivery terms; freight and duties are soft costs and go on the facility. Deposits to the builder can be progress-funded.
A signed application, 4 months of business bank statements, and the invoice or quote for the equipment. Soft-pull only, no application fee. The quote lets the advisor identify the asset and structure the facility around it.
The Operator's Guide
The Operator's Guide to Commercial Equipment Financing
The gap between the app-only financier and the institutional desk
The equipment-financing web is split in two, and neither half is built for you. On one side, app-only vendor and broker financiers approve a forklift or a single machine in hours — but cap out around $250K–$500K and usually tie you to one dealer's quote. On the other, asset-backed specialists write $5M–$100M checks for AI data-center buildouts and little else. The independent operator running $2M to $45M, buying a CNC line, a fleet of trucks, or an imaging suite, lives in the gap between them. That mid-ticket, mixed-equipment space is exactly where real equipment financing belongs.
The equipment secures itself
Here’s the thing most lenders won’t put up front: the equipment secures itself. A press brake, a tractor, an imaging system — these are real, resaleable assets, and they can carry their own loan. That means low or no down payment, and a personal guarantee that’s the exception rather than the default. You should not be pledging your building and signing a full PG to buy a machine worth what it costs. Finance the asset on the asset, and keep your cash and your real estate where they belong. Already spent the cash on equipment you own outright? An equipment sale-leaseback pulls that capital back out while the machines keep running. And when the purchase is a whole project — several vendors, an install, a build schedule — capex financing puts all of it on one facility.
An equipment lender prices the machine, not a blended loan
A generalist bank blends your whole loan at its riskiest layer and prices accordingly. An equipment lender prices the machine in its own wheelhouse — it knows what the asset is worth and what it produces. And because the financing is vendor-neutral, you compare competing real term sheets on the same equipment instead of taking the single number the dealer hands you. The asset sets the terms, not the salesperson.
Equipment runs on a delivery clock
Equipment also runs on a delivery clock, and early-purchase pricing expires. Once the file and the quote are in, funding can land in as little as 2 days — fast enough to hold the window. And the equipment layer is rarely the whole plan: it anchors a structure that stacks working capital for the ramp, A/R for receivables, and owner-occupied real estate — one application, one specialist desk, a structure that reaches $20M+.
Above $1M, what changes
The file changes before the equipment does. Under $1M a lender reads four months of deposits and the quote. Above $1M, for an operator at $10M+ in revenue, the lender reads two years of financials, the interims, and the story — what the equipment does to revenue in year one — and comes back with a proposal, not a quote. The structure widens too: operating or capital lease, 100% of hard and soft costs, progress payments during a build. If the structure words are new, the lease structures guide walks every one.
Financing the Growth? Cover the Risk That Comes With It.
A new facility, more equipment, and a bigger crew change your risk profile the moment the capital lands. Our sister company, Insurance Service 365, handles commercial coverage for operators scaling exactly like this — so the growth you just financed is protected.
Explore commercial insurance